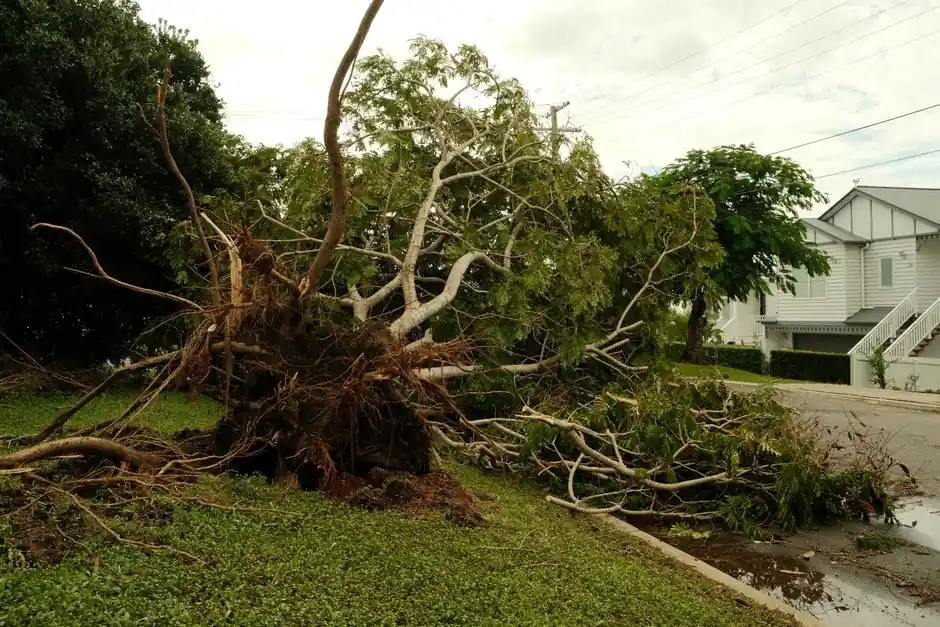
To file a storm damage roof insurance claim in Maryland, you contact your insurer, document the damage with photos and dates, get a licensed contractor's estimate, and submit the claim before your policy's deadline. Most Maryland policies require you to file within one year of the storm date, and the entire process from first call to final payout takes 30 to 90 days. This guide walks you through each step, explains what adjusters look for, and covers what to do if your claim is denied.
We have helped homeowners across Maryland navigate storm damage roof insurance claims after hurricanes, nor'easters, and summer hail events. The process is not complicated, but the details matter. Miss a deadline or skip documentation, and you give the insurance company a reason to reduce or deny your payout.
Step 1: Document the Damage Immediately
Documenting storm damage immediately is the single most important thing you can do to protect your claim in Maryland. Insurance adjusters are trained to look for evidence that damage existed before the storm or that you neglected maintenance. Your photos and notes are your best defense.
Start with wide shots of your roof from the ground, then zoom in on specific damage: missing shingles, cracked flashing, dented gutters, granules in your downspouts. Take photos of any interior water stains, ceiling cracks, or damp attic insulation. Write down the date and time of the storm, the type of weather (hail, wind, falling limbs), and when you first noticed the damage.
Do not climb onto your roof to take photos. Falls are the leading cause of injury during storm cleanup, and your insurance company does not require you to risk your safety. Ground-level photos and interior shots are enough to start the claim. If you need a closer look, call a professional for a Roof Inspection in Maryland.
Keep a folder - digital or paper - with all your documentation. Every conversation with your insurer should be logged: who you spoke to, what they said, and the date. If there is a dispute later, this record is invaluable.
Step 2: Review Your Maryland Homeowners Policy
Your Maryland homeowners policy determines what is covered, how much you will receive, and how long you have to file. Most standard policies cover damage from wind, hail, and falling objects. Flood damage is almost never covered under a standard policy - you need separate flood insurance through the National Flood Insurance Program or a private carrier.
Find your policy's declarations page. It lists your dwelling coverage limit (what the insurer will pay to repair or replace your roof), your deductible, and any endorsements. In Maryland, a common deductible for storm damage is 1% to 2% of your home's insured value. On a $400,000 home, that is $4,000 to $8,000 out of pocket before insurance pays anything.
Check for a separate windstorm or hurricane deductible. Many Maryland policies have a percentage-based deductible for named storms, which can be higher than your standard deductible. Knowing this number before you file prevents surprises.
Also look at your policy's loss settlement clause. Actual Cash Value (ACV) pays you the depreciated value of your roof - what it was worth before the storm. Replacement Cost Value (RCV) pays what it costs to replace the roof today. RCV policies cost more upfront but pay significantly more on a claim. If your roof is more than 10 years old, the difference can be thousands of dollars.
Step 3: File Your Roof Insurance Claim
Filing your roof insurance claim in Maryland starts with a phone call or online submission to your insurer. Have your policy number, the date of the storm, and your documentation ready. The claims representative will ask what happened, when, and what damage you have observed.
You will receive a claim number. Write it down. Every future conversation will reference this number. The insurer will then assign an adjuster to inspect your property, usually within 7 to 14 days for non-emergency claims. If your roof is actively leaking and causing interior damage, tell the representative - that can accelerate the timeline.
Maryland law requires insurers to acknowledge your claim within 15 days of receipt and to approve or deny it within 45 days after receiving proof of loss. If the insurer needs more time, they must notify you in writing. These deadlines are your rights under the Maryland Insurance Article.
Do not sign anything from a contractor before your claim is approved. Some out-of-state storm chasers ask homeowners to sign a contingency contract that assigns their insurance rights to the contractor. Maryland law gives you the right to cancel such contracts within a certain window, but avoiding them altogether is simpler. Work with a local company that has a physical address and a track record in your community.
Step 4: Meet the Adjuster and Get a Contractor Estimate
Meeting the adjuster with your own contractor present is the best way to ensure a fair settlement. The adjuster works for the insurance company. Your contractor works for you. When both walk the roof together, there is less room for disagreement about scope and cost.
Schedule the adjuster visit when you can be home. Point out all the damage you documented. Ask the adjuster to explain anything you do not understand. If they say a repair is not covered, ask why and write down the reason.
Get a written estimate from a licensed Maryland roofing contractor before or immediately after the adjuster visit. The estimate should itemize materials, labor, permits, and disposal. If your contractor's estimate is higher than the adjuster's, you can submit it as a supplement. Insurers often revise their initial offer when presented with a detailed, line-item estimate from a licensed professional.
For significant storm damage - missing shingles across a large area, structural damage, or water intrusion - you may need Storm Damage Roof Repair in Maryland that goes beyond a simple patch. A contractor who specializes in storm damage knows how to document the scope so the insurer approves the full repair, not just a cosmetic fix.
How long does a roof insurance claim take in Maryland?
A roof insurance claim in Maryland takes 30 to 90 days from filing to final payment in most cases. The insurer has 15 days to acknowledge your claim and 45 days to approve or deny it after receiving proof of loss. After approval, payment typically arrives within 10 to 15 business days.
Several factors can extend the timeline. If the storm caused widespread damage across your county, adjusters may be backlogged. If your claim involves a dispute over scope or depreciation, supplements and re-inspections add weeks. Complex claims with structural damage or code upgrades can take 4 to 6 months.
You can speed things up by submitting a complete proof of loss packet the first time: photos, contractor estimate, receipts for emergency repairs, and a written summary of the damage. Incomplete submissions are the most common reason claims stall.
What if my roof insurance claim is denied in Maryland?
If your roof insurance claim is denied in Maryland, you have the right to appeal. The denial letter must state the reason - common reasons include pre-existing damage, lack of maintenance, or damage below your deductible. Read the letter carefully and identify the specific objection.
You can request a re-inspection with your contractor present. Often, the adjuster missed damage or misclassified it as wear and tear. A licensed contractor can point out storm-related damage that a desk adjuster overlooked. Submit a written rebuttal with new photos and your contractor's estimate.
If the insurer still denies the claim, you can file a complaint with the Maryland Insurance Administration. The MIA investigates consumer complaints and can mediate disputes. You can also hire a public adjuster, who works for you on a contingency fee (typically 10% to 15% of the settlement) to negotiate on your behalf.
Do not give up after the first denial. Many denied claims are overturned on appeal when homeowners provide better documentation or a professional second opinion. We have seen claims go from denied to fully approved after a proper inspection revealed damage the original adjuster missed.
Common Mistakes Maryland Homeowners Make
The most common mistake is waiting too long to file. Maryland policies typically require you to file within one year of the storm date, but some have shorter windows. If you wait until you notice a ceiling stain six months later, you may have already missed the deadline.
Other mistakes we see regularly:
- Paying a contractor before the claim is approved. Never pay in full upfront. A deposit for materials is normal; full payment before work is not.
- Signing a contingency contract with an out-of-state storm chaser. These contracts assign your insurance rights to the contractor and often lead to disputes.
- Accepting the first offer without a second opinion. Initial offers are often based on a quick visual inspection and may miss hidden damage.
- Not documenting the storm date. Without a date, the insurer may argue the damage predates your policy or falls outside the filing window.
- Ignoring maintenance records. If your roof was already in poor condition, the insurer may reduce your payout. Keep receipts for repairs and inspections.
One more: do not assume your claim is too small to file. Even a $3,000 repair is worth claiming if you have already met your deductible through other damage. Talk to your insurer before deciding.
When to Call a Professional
Call a professional when the damage is more than a few missing shingles, when water is entering your home, or when your insurer's offer seems low. A licensed roofing contractor can inspect your roof, document the damage properly, and provide an estimate that holds up to scrutiny.
We handle storm damage roof insurance claims across Maryland every week. Our team walks the roof with your adjuster, provides line-item estimates, and communicates directly with your insurer so you do not have to. If your claim is denied, we can perform a second inspection and help you build an appeal.
If you are in an area hit hard by recent storms, we may already be working nearby. We serve homeowners throughout the state, including Roofing in Annapolis and the surrounding communities, where nor'easters and summer squalls are a regular threat. Whether you need a quick repair or a full replacement, we can help you get the claim moving.
For urgent leaks or structural damage, we also offer Emergency Roofing Services in Maryland to stop water intrusion before it causes more damage. The sooner you act, the stronger your claim.
Frequently Asked Questions
How do I file a storm damage roof insurance claim in Maryland?
Call your insurer, provide your policy number and storm date, and submit photos and a contractor estimate. The insurer assigns an adjuster within 7 to 14 days. You must file within one year of the storm, though some policies have shorter windows.
Does insurance cover storm damage roof repair in Maryland?
Yes, most Maryland homeowners policies cover wind, hail, and falling-object damage. Flood damage requires separate flood insurance. Your deductible - often 1% to 2% of your home's insured value - applies before the insurer pays.
What if my roof insurance claim is denied in Maryland?
You can appeal the denial, request a re-inspection with your contractor, or file a complaint with the Maryland Insurance Administration. Many denials are overturned when homeowners provide better documentation or a professional second opinion.
How long does a roof insurance claim take in Maryland?
Most claims take 30 to 90 days from filing to payment. The insurer has 15 days to acknowledge and 45 days to approve or deny after proof of loss. Complex claims with disputes can take 4 to 6 months.
Can I file a claim for a roof that is 15 years old?
Yes, but your payout depends on your policy's loss settlement clause. Actual Cash Value policies pay depreciated value, which may be low. Replacement Cost Value policies pay full replacement cost regardless of age, minus your deductible.
Get Help with Roofing in Maryland
If your roof has storm damage, we can inspect it, document the damage, and work with your insurer to get the claim approved. We know what Maryland adjusters look for and how to present the evidence.
Call RoofPros Maryland at (833) 409-1163 to schedule your inspection. We will tell you honestly whether you have a claim worth filing and what to expect from start to finish. For more about our full range of services, visit our Roofing in Maryland page.